Monday, November 22, 2010

October 2010 Top Producers

Coldwell Banker Sea Coast Realty is pleased to announce our Top Producers for October 2010.

Wilmington Office
Top Listing Agent - Sherri Pickard
Top Selling Agent - Jennifer Farmer
Top Listing Team - Jack Gale Team
Top Selling Team - Kay Baker Team

Carolina Beach Office
Top Listing Agent - Sherri Pridgen
Top Selling Agent - Julie Damron
Top Listing Team - Shawndy Conway & Jessica Keenan
Top Selling Team - Shawndy Conway & Jessica Keenan

North Brunswick Offices
Top Listing Agent - Ginger Harper
Top Selling Agent - Lynda Haraway
Top Listing Team - Emily Willetts Team
Top Selling Team - Dennis and Penny Krueger Team

Onslow/Pender Offices
Top Listing Agent - Jenna Morton
Top Selling Agent - Christina Pitz
Top Listing Team - Roger Mitchell Team
Top Selling Team - Roger Mitchell Team

Hampstead Office
Top Listing Agent - Janeise Collins

Leland Office
Top Listing Agent - Karen Schwartz
Top Selling Agent - Karen Schwartz

South Brunswick Office
Top Listing Agent - Jerry Arnette
Top Selling Agent - Monroe Enzor
Top Listing Team - Scott Haigler and Jeanette Haigler Team
Top Selling Team - Scott Haigler and Jeanette Haigler Team

Top New Home Sales Associate
Justin Ash

October 2010 OVERALL TOP PRODUCERS
Roger Mitchell
Kay Baker
Alex Paen
Jack Gale
Christina Pitz
Dennis and Penny Krueger
Lynda Haraway
Anna Garcia
Chris Baynes
Chuck Lukoski

Labels: , , , , , ,

Wednesday, November 10, 2010

Flapjack Fundraiser to Benefit Cape Fear Habitat for Humanity


Saturday, December 4, 2010, Coldwell Banker Sea Coast Realty is holding a Flapjack Fundraiser at the Applebee's Neighborhood Bar & Grill on 1113 New Pointe Blvd. in Leland, NC. From 7:30am to 10:00am, Applebee's will be serving up short stacks of pancakes for a TALL cause.

All proceeds from this event will go to build a Cape Fear Habitat for Humanity home sponsored by Coldwell Banker Sea Coast Realty. The home is already well underway in Wilmington, NC, but we still need your support!

Tickets are just $7 each, so round up your friends and family and fill your bellies with flapjacks for a good cause.

To purchase tickets or for more information, call Sea Coast Realty's Leland, NC office at (910) 371-1181 or toll free 1-866-508-1181.

Labels: , , , , , , , ,

Friday, October 22, 2010

Jonathan Swanson earns North Carolina Short Sale Specialist Certification

Jonathan Swanson with Coldwell Banker Sea Coast Realty in Wilmington, NC recently earned his North Carolina Short Sale Specialist certification. The Certified Short Sale Specialist (CSSS) Seller agent designation is the first and only short sale designation specific to the state of North Carolina.

Many North Carolina homeowners find themselves owing more on their properties than they could sell for today. As a CSSS designee, Swanson is a real estate professional that is dedicated to helping these homeowners. Swanson understands the short sale process, transactional entities, and who the true short sale decision makers are. He can also identify predatory servicing tactics and guide the consumers to the appropriate NC state regulatory agencies if necessary.

Labels: , , , , , , ,

Thursday, October 21, 2010

Find the Home Loan that Fits Your Needs

Article From BuyAndSell.HouseLogic.com


By: G. M. Filisko


Published: February 10, 2010


Understand which mortgage loan is best for you so your budget is not stretched too thin.

It's easier to settle happily into your new home if you're confident you can afford it. That requires that you understand your mortgage financing options and choose the loan that best suits your income and ability to tolerate risk.

The basics of mortgage financing
The most important features of your mortgage loan are its term and interest rate. Mortgages typically come in 15-, 20-, 30- or 40-year lengths. The longer the term, the lower your monthly payment. However, the tradeoff for a lower payment is that the longer the life of your loan, the more interest you'll pay.


Mortgage interest rates generally come in two flavors: fixed and adjustable. A fixed rate allows you to lock in your interest rate for the entire mortgage term. That's attractive if you're risk-averse, on a fixed income, or when interest rates are low.

The risks and rewards of ARMs

An adjustable-rate mortgage does just what its name implies: Its interest rate adjusts at a future date listed in the loan documents. It moves up and down according to a particular financial market index, such as Treasury bills. A 3/1 ARM will have the same interest rate for three years and then adjust every year after that; likewise a 5/1 ARM remains unchanged until the five-year mark. Typically, ARMs include a cap on how much the interest rate can increase, such as 3% at each adjustment, or 5% over the life of the loan.


Why agree to such uncertainty? ARMs can be a good choice if you expect your income to grow significantly in the coming years. The interest rate on some-but not all-ARMs can even drop if the benchmark to which they're tied also dips. ARMs also often offer a lower interest rate than fixed-rate mortgages during the first few years of the mortgage, which means big savings for you-even if there's only a half-point difference.


But if rates go up, your ARM payment will jump dramatically, so before you choose an ARM, answer these questions:
•How much can my monthly payments increase at each adjustment?

•How soon and how often can increases occur?

•Can I afford the maximum increase permitted?

•Do I expect my income to increase or decrease?

•Am I paying down my loan balance each month, or is it staying the same or even increasing?

•Do I plan to own the home for longer than the initial low-interest-rate period, or do I plan to sell before the rate adjusts?

•Will I have to pay a penalty if I refinance into a lower-rate mortgage or sell my house?

•What's my goal in buying this property? Am I considering a riskier mortgage to buy a more expensive house than I can realistically afford?


Consider a government-backed mortgage loan

If you've saved less than the ideal downpayment of 20%, or your credit score isn't high enough for you to qualify for a fixed-rate or ARM with a conventional lender, consider a government-backed loan from the Federal Housing Administration or Department of Veterans Affairs.


FHA offers adjustable and fixed-rate loans at reduced interest rates and with as little as 3.5% down and VA offers no-money-down loans. FHA and VA also let you use cash gifts from family members.


Before you decide on any mortgage, remember that slight variations in interest rates, loan amounts, and terms can significantly affect your monthly payment. To determine how much your monthly payment will be with various terms and loan amounts, try REALTOR.com's online mortgage calculators.

More from HouseLogic

Evaluate Your Adjustable Rate Mortgage

Show Your Support for FHA

Other web resources

How much home can you afford?


Why ask for an FHA loan?

G.M. Filisko is an attorney and award-winning writer who's opted for both fixed and adjustable-rate mortgages. A frequent contributor to many national publications including Bankrate.com, REALTOR® Magazine, and the American Bar Association Journal, she specializes in real estate, business, personal finance, and legal topics.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , , , ,

Wednesday, October 20, 2010

Melanie Cameron earns North Carolina Short Sale Specialist Certification

Melanie Cameron with Coldwell Banker Sea Coast Realty in Wilmington, NC, recently earned her North Carolina Short Sale Specialist certification. The Certified Short Sale Specialist (CSSS) Seller agent designation is the first and only short sale designation specific to the state of North Carolina.

Many North Carolina homeowners find themselves owing more on their properties than they could sell for today. As a CSSS designee, Cameron is a real estate professional that is dedicated to helping these homeowners. Cameron understands the short sale process, transactional entities, and who the true short sale decision makers are. She can also identify predatory servicing tactics and guide the consumers to the appropriate NC state regulatory agencies if necessary.

Labels: , , , , , , ,

Tuesday, October 19, 2010

September 2010 Top Producers

Coldwell Banker Sea Coast Realty is pleased to announce our Top Producers for September 2010.

Wilmington Office
Top Listing Agent - Tammy Barnes
Top Selling Agent - Jennifer Farmer
Top Listing Team - Jack Gale Team
Top Selling Team - Jack Gale Team

Carolina Beach Office
Top Listing Agent - Ron Barnello
Top Selling Agent - Judy Odom
Top Listing Team - Shawndy Conway & Jessica Keenan
Top Selling Team - Shawndy Conway & Jessica Keenan

North Brunswick Offices
Top Listing Agent - Hank Troscianiec
Top Selling Agent - Lynda Haraway
Top Listing Team - Dennis and Penny Krueger Team
Top Selling Team - Emily Willetts Team

Onslow/Pender Offices
Top Listing Agent - Jenna Morton
Top Selling Agent - Christina Pitz
Top Listing Team - Roger Mitchell Team
Top Selling Team - Roger Mitchell Team

Hampstead Office
Top Listing Agent - Janeise Collins
Top Selling Agent - Ed Pullen

Leland Office
Top Listing Agent - Edward Wood
Top Selling Agent - Karen Schwartz

South Brunswick Office
Top Listing Agent - Evelyn Madison
Top Selling Agent - Jimmie Pendergrass
Top Listing Team -
Scott Haigler and Jeanette Haigler Team
Top Selling Team - Tom Shoaf Team

Top New Home Sales Associate
Chris Cunningham and Tom Craigg

September 2010 OVERALL TOP PRODUCERS
Jack Gale
Roger Mitchell
Christina Pitz
Cynthia Strickland
Rand Burchfield
Jennifer Farmer
Shawndy Conway & Jessica Keenan
Wendy Shorter-Bridges
Lynda Haraway
Kay Baker

Labels: , , , , , ,

Sunday, October 17, 2010

7 Steps to a Stress-free Home Closing

Article From BuyAndSell.HouseLogic.com


By: G. M. Filisko


Published: February 10, 2010


By doing homework in advance, you'll understand what you're asked to sign when you close the sale of your home.

You've already cleared several hurdles by finding the right home, negotiating the best price, and securing favorable financing. The last obstacle on your homebuying track is the closing, which can be both tedious and tense. By knowing what to expect and doing some legwork, you can put your closing behind you. These seven steps will guide you through a smooth closing.

1. Set a closing date
Your real estate agent will work with the seller's agent and title company to schedule your closing date. Be sure it meshes with the end of your lease or the sale of your existing home and a time when you'll able to play hooky from work. If you're tight on cash, schedule your closing for the end of the month because that's when you'll have to pay the least amount of interest at the closing table.

2. Gather your funds

You may be required to bring funds to the closing. If they're not easily accessible, arrange early to transfer them to a liquid account to avoid last-minute problems. If the title company requires the funds in the form of a cashier's check, also leave time to stop by the bank and pick one up.

3. Purchase title insurance
Title insurance protects the policyholder against trouble with a home's title. Your lender will insist that you purchase a policy to protect it. You should also consider purchasing what's called an owner's title policy from the same insurer, which protects you from fraudulent claims against your ownership and errors in earlier sales. In some areas, sellers traditionally pay for the buyer's title policy. Shop online at Closing.com, EasyTitleQuote.com, and FreeTitleQuote.com. If your home has been sold within the past few years, ask the prior owner's insurance company for a reissue discount.

4. Line up homeowners insurance
Get quotes and compare policies to be sure coverage will be in effect by your closing date. An annual policy should run $500-$1,000, depending on your home's size, age, and amenities. If you live in an area where natural disasters occur, like earthquakes, floods, or hurricanes, you'll need separate insurance to protect your home.

5. Review your good-faith estimate and HUD-1 settlement sheet
Your lender must provide a good-faith estimate of your closing fees. Some of those fees can't change, and others can rise by 10%. Before you go to the closing, read your good-faith estimate, compare it with your HUD-1 settlement statement, and question any fees that increased.

6. Do a walk-through
Schedule an appointment to walk through the home one last time just before your closing. Make sure repairs you requested have been made, no major changes have occurred since you last viewed the property, and that the sellers left anything they agreed to leave and took all their belongings.

Also test electronics and appliances, such as the doorbell, dishwasher, washer and dryer, and oven, to ensure they're functioning properly. Do the same with the hot water heater and heating and air conditioning systems. Walk the yard to be sure no plants or shrubs have been removed.

7. Resolve issues identified in your walk-through
If your walk-through uncovers problems, you can delay the closing until the seller corrects them. But that's often not feasible because your lease is probably over and you've already scheduled movers. Another option is to negotiate a discount to your sales price to cover the cost of the work needed. If the air conditioning is on the fritz and a contractor says the repair will cost $500, ask that the sales price be reduced by that amount. If you make that request at closing, however, be ready for a delay while the title company redoes the paperwork.

A third option: Have the title company hold a portion of the seller's proceeds in escrow until the dispute is resolved. Once that happens, the funds will be released to you or the seller, depending on the outcome.

More from HouseLogic
Do you have the right amount of homeowners insurance?
Shop for an umbrella policy when you shop for homeowners insurance

G.M. Filisko is an attorney and award-winning writer who has endured several property closings, but the easiest was done through the mail. A frequent contributor to many national publications including Bankrate.com, REALTOR® Magazine, and the American Bar Association Journal, she specializes in real estate, business, personal finance, and legal topics.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , , ,

Friday, October 15, 2010

Keep Your Home Purchase on Track

Article From BuyAndSell.HouseLogic.com


By: G. M. Filisko


Published: March 30, 2010


You've found your dream home. Make sure missteps don't prevent a successful closing.

A home purchase isn't complete until you make it to the closing. Until then, the transaction can fall apart for many reasons. Here are five tips for avoiding mistakes that cause a home sale to crater.

1. Be truthful on your mortgage application
You may think fudging your income a little or omitting debts when applying for a mortgage will go unnoticed. Not true. Lenders have become more diligent in verifying information on mortgage applications. If you fib, expect to be found out and denied the loan you need to fund your home purchase. Plus, intentionally lying on a mortgage application is a crime.

2. Hold off on big purchases

Lenders double-check buyers' credit right before the closing to be sure their financial condition hasn't weakened. If you've opened new credit cards, significantly increased the balance on existing cards, taken out new loans, or depleted your savings, your credit score may have dropped enough to make your lender change its mind on funding your home loan.


Although it's tempting to purchase new furniture and other items for your new home, or even a new car, wait until after the closing.

3. Keep your job

The lender may refuse to fund your loan if you quit or change jobs before you close the purchase. The time to take either step is after a home closing, not before.

4. Meet contingencies

If your contract requires you to do something before the sale, do it. If you're required to secure financing, promptly provide all the information the lender requires. If you must deposit additional funds into escrow, don't stall. If you have 10 days to get a home inspection, call the inspector immediately.

5. Consider deadlines immovable
Get your funds together a week or so before the closing, so you don't have to ask for a delay. If you'll need to bring a certified check to closing, get it from the bank the day before, not the day of, your closing. Treat deadlines as sacrosanct.

More from HouseLogic
How maintenance adds to home values
Reducing closing stress

Other web resources
More on calculating closing costs


More on the closing process 


G.M. Filisko is an attorney and award-winning writer who wanted a successful closing on a Wisconsin property so bad that she probably made her agent rethink going into real estate. A frequent contributor to many national publications including Bankrate.com, REALTOR® Magazine, and the American Bar Association Journal, she specializes in real estate, business, personal finance, and legal topics.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , , ,

"The Real World of Real Estate"

REAL ESTATE as a Career?

Tired of working for someone else and having a limited income?

Join Us For
"The Real World of Real Estate"
Tuesday, Nov. 9, 2010
6:00pm
1001 Military Cutoff Rd, Suite 101
Wilmington, NC 28405


TOPICS:
* How do you get your real estate license?
* How much money can you make?
* How much money is required to start?
* You have your license, now what?
* Large office vs small office?

Hear about our exciting New Agent Training Program from a certified instructor.

Hear from a "Star" agent and a "New" agent.

Seating is limited - please call to reserve your space!
Contact Denise at 910-367-3325 or Amy at 910-297-9526.

Labels: , , , ,

Thursday, October 14, 2010

Realtors' Letters Add Special Touch to Honor Flight

Coldwell Banker Sea Realty associate Russ May just returned from accompanying World War II veterans to see the WWII Memorial in Washington, DC. The trip was made possible by Honor Flight Southeastern North Carolina.

Honor Flight is an amazing all-volunteer effort dedicated to demonstrating respect and admiration for surviving World War II veterans by flying them at no cost to Washington, DC to see the World War II Memorial. The Memorial was completed in 2004.

The majority of the veterans are in their 80's and some needed a little special help navigating the airport and finding their way around Washington's monuments. As a Guardian on the trip, Russ May helped veterans have a safe and comfortable journey.

"A very important and emotional part of the return trip is 'mail call' when the veterans are surprised to receive letters from their families and friends expressing their thanks and gratitude for the veterans' service," said May. A day and a half before the most recent Honor Flight trip, May found out that some of the veterans wouldn't be receiving letters and that it was too late to contact their families again.

"It would be a shame for these individuals to sit empty handed while their fellow veterans receive a package of mail," he wrote in an email to associates and staff in Coldwell Banker Sea Coast Realty's Wilmington, NC office. "If you have a moment to write a generic note to a WWII veteran, I'll make sure it gets in the right hands."

Overnight, Russ May's mailbox was filled with 54 letters expressing heartfelt gratitude. Even though the letters were addressed to perfect strangers, the writers shared personal stories of lost loved ones, family members who served during wartime, and respect for the military. "Having seen the emotion in the faces of veterans in past flights, I know your thoughts, prayers, and blessings will be warmly received, richly deserved, and much appreciated," May told his colleagues.

Russ May is one of several Realtors at Coldwell Banker Sea Coast Realty that have volunteered with Honor Flight Southeastern North Carolina. The October 13, 2010 trip was the third Honor Flight made possible by Honor Flight Southeastern North Carolina. Veterans had beautiful weather for their trip to Washington, DC. A crowd of several hundred well-wishers decked out in red, white, and blue greeted the veterans when they returned to Wilmington International Airport Wednesday evening.

For more information about Honor Flight of Southeastern North Carolina, please visit http://www.honorflightsenc.org/.

To learn more about the national Honor Flight organization, log on to http://www.honorflight.org/.

Labels: , , , , , , ,

How much is my house worth?

How much is my home worth and how fast can I sell it? Those are the first questions many home sellers ask their Realtor.

Tina Abraham with Coldwell Banker Sea Coast Realty explains that several variables influence the answer. The condition of your home, how well it's priced, and how much competition you have all play a role in what your home is worth and how quickly you can sell it.


If there are already several homes for sale in your area, Tina says it's very important to make sure that your home is the best-priced and in the best condition in your area. That will ensure that when buyers look in your area, they'll choose to look at your home.

For more information, please visit ‪SeaCoastRealty.com‬ or become our fan on Facebook.‬

Labels: , , , , , ,

Wednesday, October 13, 2010

Energy Efficient Fireplaces: Wood-Burning and Gas-Burning

Article From HouseLogic.com


By: Rich Binsacca


Published: September 21, 2010


Energy-efficient fireplaces, both wood-burning and gas, let you enjoy the glow of a fire without letting your home heating energy go up in smoke.

A traditional wood-burning fireplace adds warmth and romantic ambience to a home's interior. But most are energy hogs, converting only 15% of wood's energy into useful heat. Fortunately, new energy-efficient fireplace designs are helping wood-burning fireplaces achieve efficiency ratings of 75% or more. Fireplace inserts and gas fireplaces are even more efficient.

Energy-efficient wood-burning fireplaces

If you're adding a wood-burning fireplace, avoid the standard design, which sends too much of your home's heated air up the chimney. Consider these energy-efficient wood-burning fireplaces:

•Rumford fireplaces feature a shallow box design that reflects more heat into the room.


•EPA-rated fireplaces have good performance and high energy-efficiency ratings. They are designed to pull in outdoor air for combustion, and circulate room air around the firebox to extract as much useable heat as possible. In addition, EPA-approved wood-burning fireplaces produce much less air pollution than standard fireplaces.


•Fireplace inserts are sealed metal boxes designed to fit inside masonry fireplace openings. They use outside air for combustion, and are designed to circulate and warm inside air. Inserts burn a variety of biomass fuels, including wood and pellets. Some units are rated at 80% efficiency.


If you already own a standard wood-burning fireplace, make it more energy efficient by installing glass doors. Glass doors limit the amount of room air that is sucked into the fireplace during combustion.


Glass doors work particularly well when a fire is burning down for the night and you must leave the damper open. Otherwise, glass doors block radiant heat; keep them open when your fire is blazing. Expect to pay $300 to $500 for glass doors, installed.


In California, glass or solid metal doors are required on all fireplace openings.

Energy-efficient gas fireplaces
If you want the convenience and low maintenance of a energy-efficient gas fireplace, you have two good options:

•Direct-vent gas fireplaces, which use two-way vents that supply outside air for combustion, have energy-efficiency ratings as high as 77%. That's better than the top gas fireplaces connected to a chimney.


•Vent-free gas fireplaces are even more energy-efficient because they don't send exhaust outside. But they release a lot of moisture into inside indoor air.


Tax credits for fireplaces
Some types of fireplaces qualify for a federal tax credit of up to $1,500 until the end of 2010. After that, certain states may provide tax credits for various types of energy-efficiency improvements, including fireplaces.


Rich Binsacca is the author of 12 books on various home-related topics and is currently a contributing editor for Builder and EcoHome magazines. He has written articles for Remodeling, Home, and Architectural Record, among several others. He intermittently uses the wood-burning fireplace and the gas-fueled freestanding stove that came with his current home.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , ,

Tuesday, October 12, 2010

6 Tips for Staging Your House To Sell

A house that has been properly staged may sell faster and for more money than a home that has not been staged explains Anna Garcia of Coldwell Banker Sea Coast Realty in Jacksonville NC.


Anna's offers the following tips for staging your property:
1. Remove Clutter
2. Let in natural light
3. Use neutral paint colors
4. Remove obstacles
5. Curb appeal
6. Dress your home interior for success

Showing your home to sell is much like a job interview. That's why it's important that your home dress for success!

Labels: , , , , , ,

Monday, October 11, 2010

Costs of Adding a Fireplace

Article From HouseLogic.com


By: Rich Binsacca


Published: September 22, 2010


Installing a wood-burning, gas-burning, gel-fuel, or electric fireplace to your house costs $400 to $10,000, depending on the type of fireplace you select.

Installing a fireplace with a brick-lined hearth and a custom mantel can easily cost $10,000 or more. It's also possible to get a similar look for thousands of dollars less. Just shop for a ready-made unit and watch what you spend on the fireplace surround.

If your budget is really tight, a free-standing gel-fuel or electric fireplace eliminates installation costs. But be aware that some bare-bones alternatives don't completely succeed in mimicking a real wood fire.


Check local building codes for possible restrictions on the types of fireplaces that can be installed in your area.

Costs of a wood-burning fireplace
An open-hearth, wood-burning fireplace-like the ones you see in mountain resort hotels-requires the help of a skilled, professional mason and a budget approaching (and often exceeding) $10,000.


For an existing home, considerable renovation work is required, including a foundation to carry the weight of the firebox and chimney, and the cost of the chimney itself.


Expect to pay $7,000 to $10,000 or more.

Cost saver tip: Go for a drywall surround and a simple, wall-mounted mantle.


Costs of a gas-burning fireplace
A fireplace unit that burns natural gas or propane runs about $2,000 for the basic materials package. Installation and finishing typically add $2,500.

Cost saver tip: Switch to a simpler surround and mantle, and get a direct-vent fireplace so you don't need a chimney. Or, opt for a vent-free gas fireplace for $400 or so. Hiring a professional to install a gas line or a connection to a propane tank adds about $1,000.


Your least-expensive option
A gel-fuel fireplace or an electric fireplace starts under $400. With a portable unit, that's the total cost since the fireplace is ready to use once you remove the packaging.


Because there's no flue or chimney, it's easy to install TVs or other electronic gear directly above an electric fireplace. If you include a mantel package, expect to pay $800 to $1,600. One perk available: sound effects that mimic the crackle and pop of a real fire.

Ongoing costs

Estimate your energy costs by using a fuel cost comparison calculator. Gel fuel, not included in the calculator, costs $3 per 13-ounce can, enough for three hours.

For a wood-burning fireplace, figure on $100 to $200 a year for chimney cleaning. Gas fireplaces need an annual service check ($100 to $150) plus a chimney inspection. Gel-fuel and electric fireplaces don't need regular maintenance.

Tax credits for fireplaces
Through Dec. 31, 2010, you may qualify for a federal tax credit for 30% of your costs, up to $1,500, if you install a wood-burning fireplace that's at least 75% fuel-efficient.


Rich Binsacca is the author of 12 books on various home-related topics and is currently a contributing editor for Builder and EcoHome magazines. He has written articles for Remodeling, Home, and Architectural Record, among several others. He intermittently uses the wood-burning fireplace and the gas-fueled freestanding stove that came with his current home.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , ,

Saturday, October 09, 2010

Adding a Fireplace: Return on Investment

Article From HouseLogic.com


By: Rich Binsacca


Published: September 22, 2010


Installing a fireplace is a popular project, but don't expect a significant return on your investment.

With costs ranging up to $10,000 for a traditional brick hearth and mantel, installing a fireplace is a serious investment. If you're wondering if you'll get a return on that investment, the answer is: probably not.

While intangible benefits such as comfort and ambience may make a fireplace addition worth the cost for you, consumer attitudes toward fireplaces are changing. Here are the facts:

Fireplaces no longer are preferred features
•In 2007, the National Association of REALTORS survey of homebuyers' preferences listed fireplaces as the most preferred home feature. Almost 46% of homebuyers said they would pay extra (a median of $1,220) for a house with at least one fireplace, the most popular "desired feature" in the survey. However, more recent surveys from the National Association of Homebuilders show that support is slipping, and REALTOR® Magazine recently put fireplaces No. 1 on the list of "Home Fads That Are Falling Out of Style." That means chances of receiving price support for your fireplace addition when you sell your home are diminishing.


•According to the U.S. Census Bureau, 53% of new homes built in 2008 included at least one fireplace. That's down from a peak of 66% in 1990, although the numbers may also reflect builders' attempts to save costs for development houses.


•A fireplace isn't calculated separately in a professional home appraisal, making it difficult to assign increased value from your investment.


Match your fireplace budget to your house

When you estimate how much a fireplace might add to the value of your house, consider your home's overall value. A $10,000 fireplace holds its value in a $1 million house because buyers expect this feature in an upscale home. But a $10,000 fireplace might not be such a crucial component of a $100,000 house, especially if features that potential buyers consider more important are lacking.

Get value from your fireplace investment

•Put a new fireplace in a room other than the kitchen--usually the family room or great room.


•Locate a fireplace in a smaller, easy-to-heat room such as an office, guest bedroom, or master bedroom.


•Equip your fireplace with energy-efficient glass doors and an exterior venting system that prevents heated air from being pulled out of rooms.


Rich Binsacca is the author of 12 books on various home-related topics and is currently a contributing editor for Builder and EcoHome magazines. He has written articles for Remodeling, Home, and Architectural Record, among several others. He intermittently uses the wood-burning fireplace and the gas-fueled freestanding stove that came with his current home.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , ,

Thursday, October 07, 2010

Wood-Burning Fireplace Inserts Save Energy

Article From HouseLogic.com


By: Wendy Paris


Published: September 22, 2010

Install a wood-burning fireplace insert if you want to keep the magic of a wood fire but make your open fireplace more energy efficient.

If your house has a traditional fireplace, you might love the authentic crackle of the fire and the warm ambience that fills your rooms. But that romantic hearth is costing you money-90% of the heat generated by an open fire goes right up the chimney.


The remedy? A wood-burning fireplace insert captures the good vibes and keeps your heat from going up in smoke.

A wood-burning fireplace insert is a metal box that fits inside your existing masonry fireplace opening. A decorative flange fits around the outside edges so that no gaps appear between the unit and the sides of the fireplace. A new metal chimney liner is required to carry combustion gases and smoke up through your chimney.


Fireplace inserts have clear heat-proof glass doors. The best designs circulate air within the firebox in a way that helps keep the glass clean.


Wood-burning fireplace inserts heat 1,000 to 3,000 square feet, depending on their size. Talk to your insert dealer about the size of your existing fireplace and what heating capacity you can expect from an insert.


Inserts cost $3,000 to $4,000, including installation and a chimney liner.

High marks for energy efficiency
An enclosed firebox ensures the highly efficient combustion of wood, helping you extract the most heat for the least cost. Most wood-burning fireplace inserts include a fan to help circulate room air around the firebox and release it back into the room.


A wood-burning fireplace insert helps cut heating costs by 10% to 40%. That's a savings of $64 to $255 a year for the average homeowner. Though fuel prices can fluctuate wildly, savings could be even greater if you rely on pricier electricity or fuel oil for heating, rather than natural gas or propane.


Improvements in the designs of wood-burning fireplace inserts over the past five years mean almost all new units now meet the guidelines for fuel efficiency set by U.S. Environmental Protection Agency of 60% to 80%.

Advantages of a fireplace insert
•An insert designed to heat 1,500 square feet will burn for three to five hours before you need to reload-a lot less hassle than tending an open fireplace.


•Firewood is an economical fuel in many regions, costing just $922 per year to heat a typical home when the wood is burned efficiently. If you cut the wood yourself, it might even be free. If you buy, you support local jobs.


•Efficient combustion reduces the amount of noxious gases and particulates produced by an open fireplace.


Disadvantages of a fireplace insert
•You'll still need to stack and load firewood and empty ashes periodically.


•The fire is behind glass doors rather than exposed.


•Fitting an insert into an existing fireplace opening can be tricky. In some instances, the insert may protrude beyond the fireplace surround, and you'll have to add trim to make up the difference.


•The payback period on your investment may be 15 years or longer.


Tax credits for wood-burning fireplace inserts
There's a federal tax credit available until the end of 2010 for fireplace inserts that burn wood, pellets or other biomass fuels, and are at least 75% efficient. The tax credit is good for 30% of what you spend, up to $1,500, and includes installation expenses.


The federal tax credit expires at the end of 2010. After that, certain states may provide tax credits for various types of energy-efficiency improvements, including fireplaces.


Wendy Paris is a writer in New York. She recently built a home in New York's Catskill Mountains and installed a wood stove in the living room that can heat up the entire first floor. She loves her wood stove. She's written about building her house for This Old House magazine.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , ,

Tuesday, October 05, 2010

Gas Fireplace Inserts: Pros and Cons

Article From HouseLogic.com


By: Wendy Paris


Published: September 22, 2010


Add a gas-burning fireplace insert if you want clean air and the ultimate in convenience.

Flip a switch; have fire. That's the key appeal of a gas fireplace insert. You still enjoy real flames, but without the hassles of solid fuel. There is no firewood to stack, bags of pellets to dump, and no ashes to clean out. The air inside your house and in your neighborhood stays clean, too. No wonder that about 70% of all hearth products-fireplaces, inserts, and artificial log sets-now burn gas.

Unlike old decorative gas fireplaces, today's gas inserts are heat-producing dynamos that use natural gas or propane to power a steady flame dancing on fake logs, decorative modern glass chips, or stones behind a sealed glass face.

Gas inserts are available as vented units or unvented units.

•Direct-vent units are safest. They draw in outside air to keep the flame burning and exhaust all the combustion gases and water vapor released by burning gas.


•Ventless inserts have a higher efficiency rating (92% to 99% vs. 60% to 80% for direct-vent inserts) because no heat escapes up the chimney. But the exhaust fumes and moisture released from burning gas stay in your house, which may be a cause for concern.


Most ventless gas fireplace inserts are considered safe for homeowners because they include an oxygen-depletion sensor that turns gas off before carbon monoxide reaches dangerous levels in the room. Nevertheless, some states don't allow ventless gas units.


Check your local building codes regarding the types of fireplace inserts allowed in your area.

Capacity and cost of inserts

A gas-burning fireplace insert heats 1,000 to 3,000 square feet, depending on its size. Talk to your insert dealer about the size of your existing fireplace and what heating capacity you can expect from an insert.

Inserts cost $3,000 to $4,000, including installation and a chimney liner.

Upsides to a gas fireplace insert
•Gas fireplace inserts can be used in masonry or prefab fireplaces; they can be vented through the existing chimney (or a wall for a free-standing unit).


•Gas inserts require little maintenance beyond an annual $75 to $125 checkup. Its best application is for zone heating-turning up the gas in the room you're in and lowering the thermostat in the rest of your house.


•There's a definite green factor--they burn with a 65% to 99% efficiency rating, which means very little pollution or smoke.


•There's no ash or creosote produced with a gas-burning unit.


On the downside
•Gas inserts means you're burning fossil fuel, making the unit ineligible for the federal tax credit (which expires at the end of 2010) and unattractive if you're eager to reduce your carbon footprint.


•Propane is an expensive heating fuel-you won't save money heating your whole house with a gas insert.

•You'll spend more on gas or propane than you would on wood or pellets to produce the same amount of heat.


•A gas insert burns fossil fuel, so it doesn't qualify for the 30% tax credit available for inserts that burn biomass, such as wood or pellets.


Wendy Paris is a writer in New York. She recently built a home in New York's Catskill Mountains and installed a woodstove in the living room that can heat up the entire first floor. She loves her wood stove. She's written about building her house for This Old House magazine.

Reprinted from HouseLogic (houselogic.com) with permission of the NATIONAL ASSOCIATION OF REALTORS (R).Copyright 2010. All rights reserved.

Labels: , , , , , ,

Monday, October 04, 2010

Sea Coast Realty Breaks Ground on New Habitat Home

On Saturday, September 25, 2010, a small crowd gathered in an empty lot on Corbett Street in Wilmington, NC. Despite the early hour, the group was buzzing with excitement, because soon a new Habitat for Humanity home would begin to take shape.

Coldwell Banker Sea Coast Realty associates, staff, and their families joined with representatives and volunteers from Cape Fear Habitat for Humanity to say prayers and well wishes before the ceremonial first shovels of earth were turned. When the ceremony ended, an army of volunteers armed with shovels, including the homeowner and her daughter, were hard at work digging the footers for the new home.

The new homeowners hope to be in their completed Habitat home by January 2011. The home is sponsored by Coldwell Banker Sea Coast Realty.


Check out our photos of the occasion on our Facebook photo album.

See news media coverage of the groundbreaking ceremony:

Ceremony today to begin ground breaking of Habitat for Humanity home (Star News)

Mom and daughter break ground for new home (WECT)

Can you dig it - Coldwell Banker Sea Coast Realty sponsors new Habitat project (Star News)

Labels: , , , , , ,

Thursday, September 30, 2010

Sea Coast Realty Donation to Hospital Fundraiser

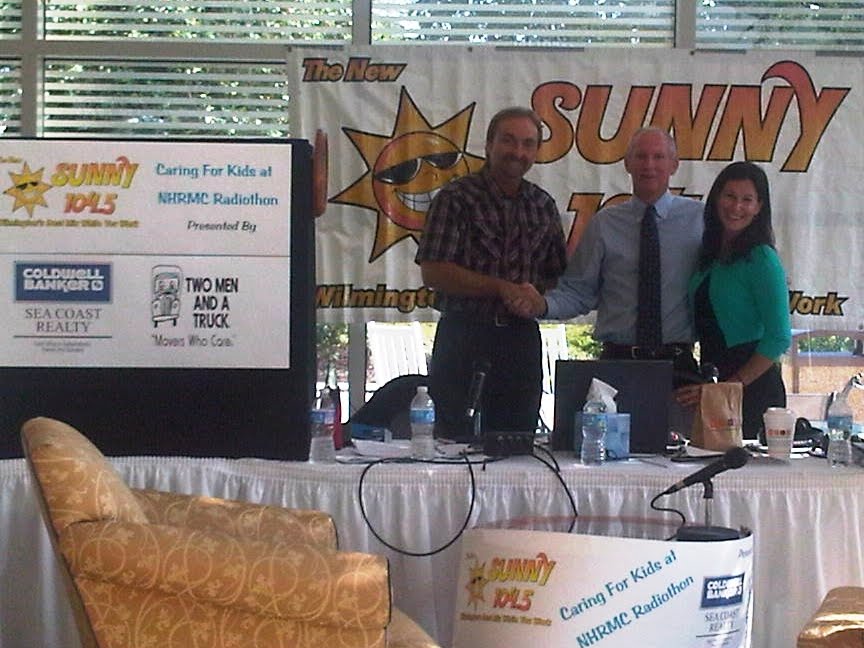
Brian Moxey, Director of Business Development, recently presented Sunny 104.5 FM radio personalities Craig and Sheila with a $1,500 donation from Coldwell Banker Sea Coast Realty for the Betty H. Cameron Women’s and Children’s Hospital.

Sea Coast Realty was a primary sponsor of the radiothon fundraiser for the hospital at New Hanover Regional Medical Center in Wilmington, North Carolina.

The 2-day event raised almost $28,000 for the purchase of seven cardiac monitoring systems for the newly-renovated pediatric area in the Emergency Department.

If you missed the Radiothon, you can still contribute by contacting Kristal McHugh at (910)815-5003 or or by visiting www.nhrmcfoundation.org/giveonline and selecting "Radiothon" on the donation form.

Photo courtesy of Shannon Lee.

Labels: , , , , ,

Huge Indoor Yard Sale to Benefit HABITAT FOR HUMANITY

More than 325 agents & staff at Coldwell Banker Sea Coast Realty are cleaning out our closets and garages to benefit Cape Fear Habitat for Humanity!

GIANT INDOOR YARD SALE
Saturday, October 2, 2010
7:30am-Noon

894 South Kerr Ave #5
Wilmington, NC 28403
Click here for a map.

It's located in Crossroads Center at the corner of Wilshire Ave. and Kerr Ave., behind Harris Teeter. Just look for the aqua metal roofs.

This huge sale is indoors and air-conditioned, so it's not exactly a "yard sale." However, if you need a yard, we'll be happy to sell you one of those too!

Cash and local checks with ID.

We need your junk!
Want to clean out your closet or garage to benefit Habitat for Humanity too? We're accepting donations at above address Thursday, Sept. 30 (10am-4pm) and Friday, Oct. 1 (10am-1pm). Just back your vehicle up to our doors (look for the orange cones) and we'll be happy to unload your donated items.

Questions? Reach our Wilmington office at (910) 799-3435.

Labels: , , , , , ,